Owning a home was once seen as a big achievement, a symbol of success and security. Families celebrated it as a key life goal. But things have changed. With rising property prices, changing jobs, and flexible lifestyles, many are now asking: Is it better to rent or buy a home?
Let’s break it down and look at the real costs, emotions, and practical points to help you decide what works best for you.

Renting: wasting money or a smart choice?
Some people say renting is like “throwing money away.” But that’s not always true. Renting has its own set of benefits:
Lower costs at the start: You only need a small deposit, not lakhs of rupees for a down payment.
Monthly savings: Rent is often cheaper than home loan EMIs.
More freedom: You can move easily if your job or plans change.
Less risk: You don’t have to worry about house repairs, market ups and downs, or rising interest rates.
In cities like Berlin and New York, long-term renting is normal. In India, people still dream of owning a home. But as cities get more expensive, renting is becoming a smarter choice for many young people.
For example, in Mumbai or Bengaluru, a ₹1 crore flat may have an EMI of over ₹80,000, while renting a similar home could cost only ₹30,000–₹40,000. That’s a big difference.
The true costs of buying a home
Buying a home is a big dream, but it also comes with big costs. Many people forget to think about the hidden expenses.
Down payment: In cities like Mumbai or Bengaluru, a ₹1 crore flat typically requires a ₹20 lakh down payment, a sum that can wipe out years of savings.
EMIs: Monthly payments often exceed ₹80,000, compared to ₹25,000–₹40,000 for renting a similar property.
Maintenance charges: High-rise societies charge ₹5,000–₹15,000 per month for upkeep and amenities.
Property taxes: Annual taxes can range from ₹10,000 to ₹50,000, depending on location and property size.
Unexpected repairs: Major plumbing, electrical, or structural issues can cost lakhs over time, and these are the owner’s responsibility.
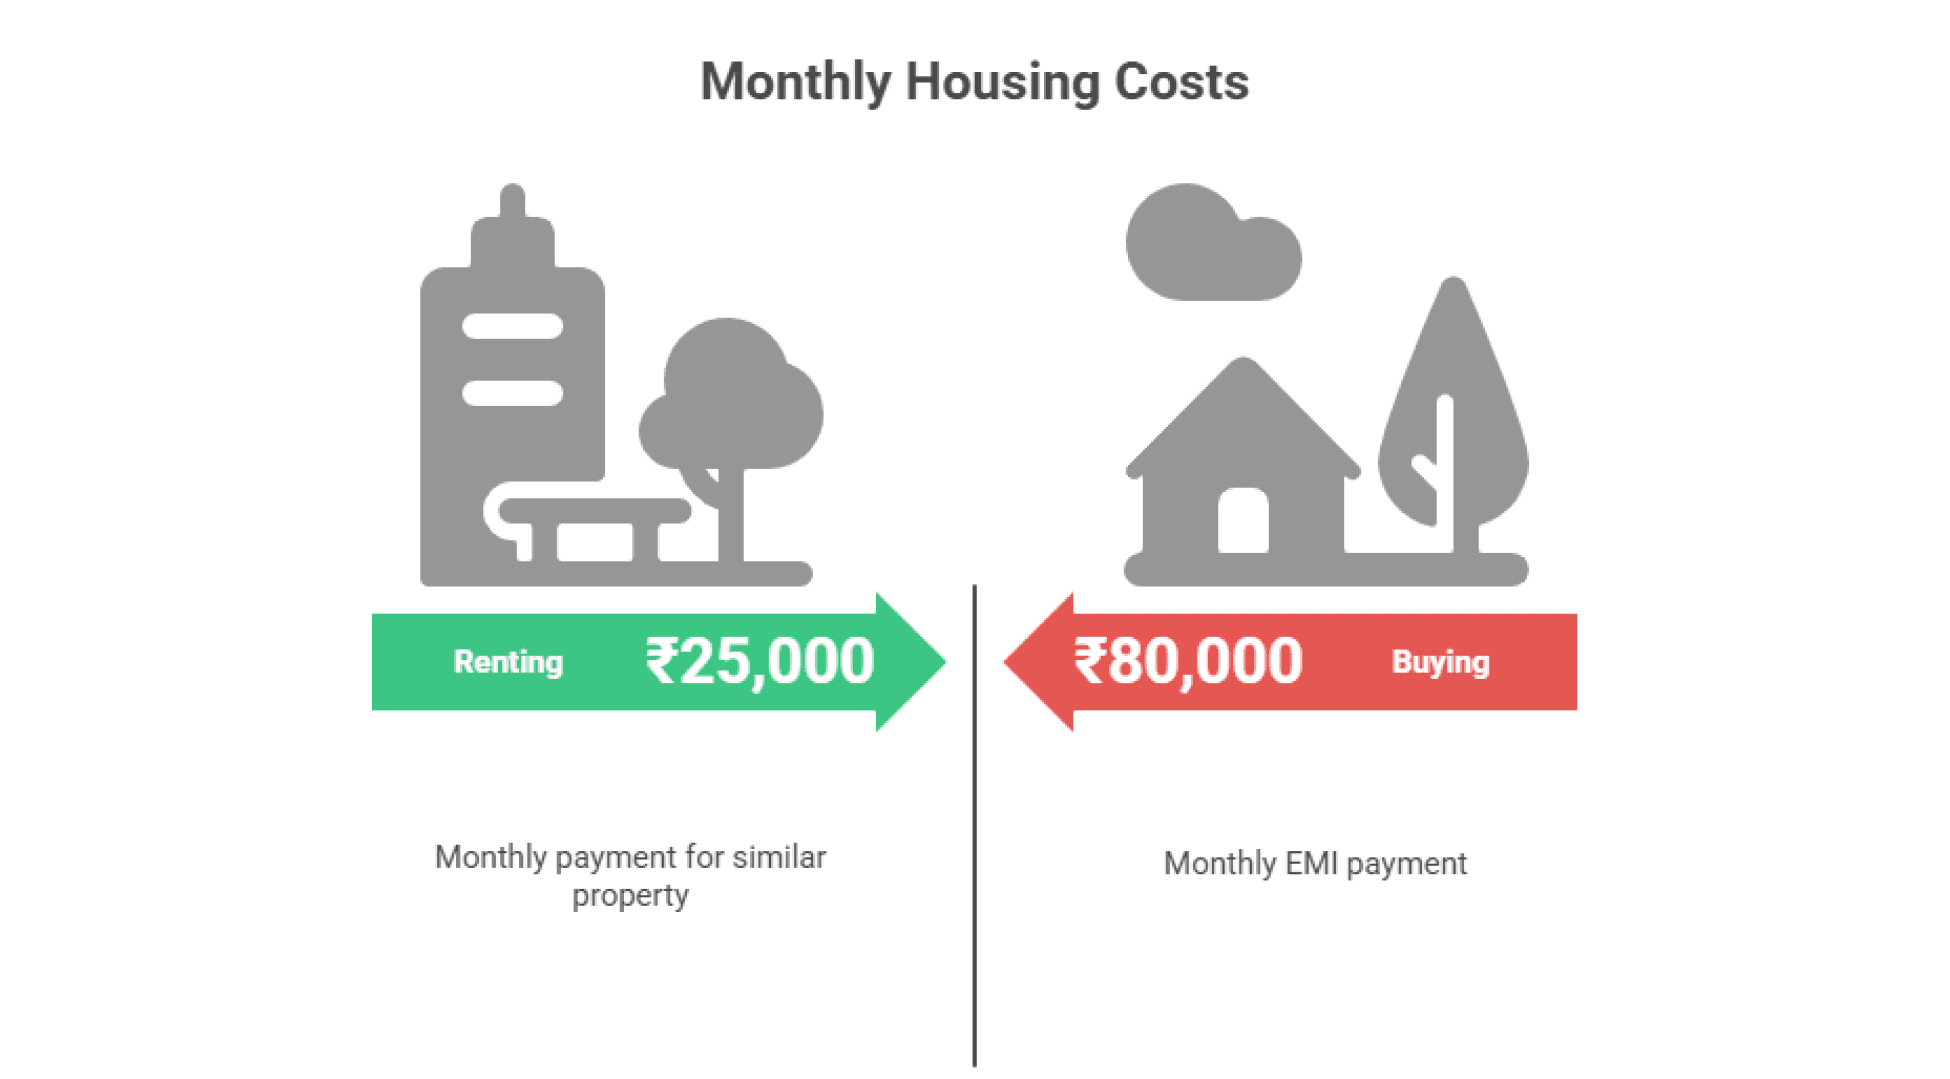
When you add up these expenses, the cost of buying can far exceed the cost of renting, especially if property values stagnate or decline. In such cases, the financial argument for renting becomes even stronger.
The emotional price tag of homeownership
Buying a home isn’t just a financial decision—it’s often an emotional milestone that reflects stability, pride, and a sense of achievement. It gives you a place that’s truly your own, where you can paint the walls, decorate freely, and build lasting memories. For many, homeownership brings peace of mind, offering long-term security and a strong foundation for family life. It also carries social value, as owning property is still seen as a mark of success and respect in many cultures. Beyond emotions, there are practical advantages too. Every EMI payment helps you build ownership in a valuable asset, and fixed-rate loans protect you from rising rents. You also enjoy the freedom to customise your space as you wish. Plus, there are tax benefits on home loan interest and principal repayments, which help you save money. In the long run, owning a home provides financial security, whether it’s for retirement, future generations, or even rental income when needed. So while the upfront cost may be high, the emotional and practical rewards of owning a home can be truly meaningful.
Rent or buy: What’s your fit?
There’s no one-size-fits-all answer. The right choice depends on your financial situation, career plans, and personal goals.
Consider these factors:
Stability vs. flexibility: Buying suits those settled in one city with a secure career. Renting is ideal for those with job mobility or uncertain plans.
Financial readiness: A ₹20–30 lakh down payment for a ₹1 crore flat can strain savings. Renting preserves liquidity and flexibility.
Long-term goals: EMIs lock in income for years, limiting other financial goals. Renting frees up funds for investments or lifestyle choices, but doesn’t build equity.
Market appreciation: If property values rise significantly, buying can be a smart investment. If not, renting may remain the better deal.
Family and community: Buying builds a permanent home for family ties. Renting supports a dynamic, mobile lifestyle.

Renting offers short-term savings and flexibility, but you’re not building an asset. Over time, rising rents and lack of ownership can outweigh the initial benefits, especially if property values appreciate.
Is homeownership still the dream?
For some, owning a home still feels like the ultimate goal. It gives emotional satisfaction, pride, and long-term safety. For others, especially young people in big cities, renting offers flexibility, lower stress, and more financial breathing room. There’s no right or wrong answer. It all depends on what fits your life best.
So, is homeownership your next step—or just one of many smart choices available to you?

Newly Launched


Pockvue Solutions Private Limited
#1, CRE Spacez, 2nd Floor, 14th Main Road,
Sector 5, HSR Layout, Bengaluru - 560102